


MEET THE SPEAKER: RAYAN BHATTACHARYA – WHAT’S NEXT FOR PAYMENTS RESILIENCE: INNOVATING SAFELY IN AN ALWAYS-ON WORLD
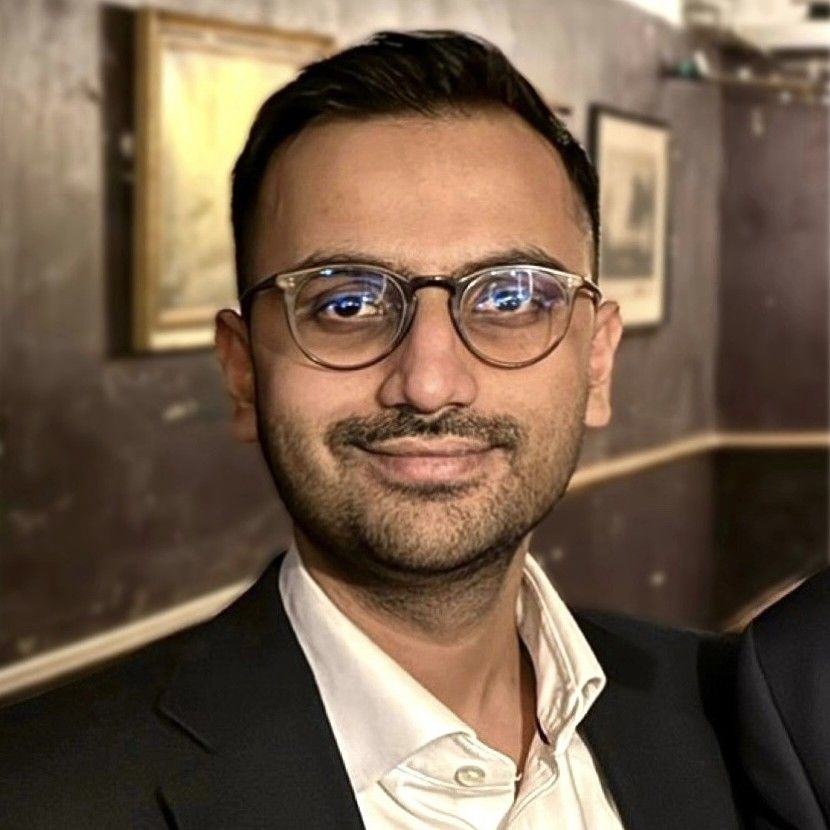
Speaker Name: Rayan Bhattacharya
What's one thing you hope attendees take away from your session?
My headline message is that resilience should be viewed as an enabler of the payments innovation agenda, not a constraint on it. But to achieve that, the industry needs to think about resilience end-to-end. A payment can depend on multiple systems, third parties, technologies and regions, but having resilient individual components does not necessarily make the overall payment service resilient. As payments become more interconnected and firms introduce technologies such as AI and blockchain, understanding those dependencies becomes critical. If we build that resilience in from the outset, it gives firms greater confidence to innovate, scale and move faster.
In one sentence, what do you do and what is your role?
Reporting into Santander’s Global/UK Head of CIB Resilience, I hold a dual role as the Head of Global Resilience Assurance, and the Resilience lead for the UK, the latter role having a particular focus on the resilience of domestic, cross-border, and DLT-based payment solutions.
What's the biggest challenge facing the industry in this area?
For the next five years, a key challenge is to encourage the industry not to tackle payments resilience in isolation. Payments are inherently interconnected, depending on a complex chain of internal and external dependencies. Equally, there is a clear drive in the industry towards frictionless, real-time, and “always on” payments. True resilience therefore requires coordination between banks, schemes, infrastructure providers, technology firms, and regulators. End-to-end resilience must be solved as a “collective action” problem.
What's one piece of advice you'd give to someone working in fintech today?
AI, digital assets, real-time payments, regulation, and new operating models are driving change, that would have traditionally taken multi-year initiatives, to now materialise in 1-2 years. In this context, it is likely that the ability to rapidly learn and continuously re-orient ourselves will keep us durable for longer than being technical experts in a single area.
What book, podcast, newsletter, or resource would you recommend to our audience?
The Incerto series of books from Nassim Nicholas Taleb! One of the best modern thinkers on risk and uncertainty, decision-making, and human psychology.
What topic will you be speaking about at FinTech Connect 2026?
I will be speaking about what’s next for payments resilience. Banks have done a lot of work in recent years to make critical payment services more resilient, across both wholesale and retail payments. The next challenge is understanding the wider ecosystem, how payments depend on other firms, technologies and infrastructure across borders. This becomes even more important as banks start using technologies such as blockchain and agentic AI in payments. I’ll explore how strong resilience can give banks the confidence to adopt these technologies safely, rather than becoming a barrier to innovation.
Just for fun: if you could have dinner with any person, past or present, who would it be and why?
Alfred Hitchcock!
What industry trend are you watching most closely?
A notable trend I am watching is the emerging gap between what technology makes possible and what regulators across regions are comfortable allowing into critical payment services.
Why is this topic particularly important right now?
There is undoubtedly a lot of interest of integrating AI, blockchain and other emerging technologies into payments. But for most major banks, payments are critical services. Hence, the question is not simply what the technology can do, but how much change regulators will be comfortable with, and how quickly. I think that will vary across markets. For global banks, the challenge will be finding a way to innovate across those different regulatory environments while maintaining a consistently high level of resilience. In many ways, evidencing resilience could become the thing that gives regulators greater confidence to allow innovation to move forward.
What's one prediction you have for the next 3-5 years?
I think resilience will become a real competitive differentiator in payments over the next few years. Unlike some banking services that can tolerate being unavailable for a period of time, payments are largely expected to be “always on.” That means the next major payments initiative your firm runs, whether that is new technology, new products, or expansion into new markets, cannot move forward unless resilience is considered at every step. If the “minimum viable business” is not resilient, the regulators will simply not approve it. For global banks, the challenge will go even further: clients will increasingly expect the same level of resilience wherever in the world they make a payment. I think the firms that can deliver that consistently across countries, payment rails, and technologies will have a real advantage.