


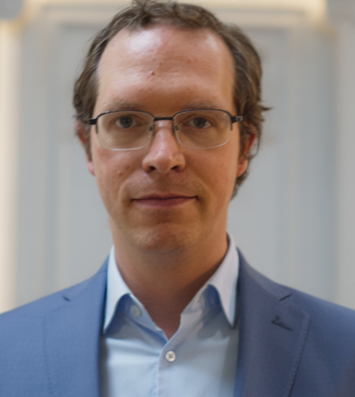
Jakob Lavrod
Lead Quantitative Risk Analyst,
Nordea
Originally a mathematical physicist specialized in Bayesian inference, since moving over to quantitative risk in banking, Jakob has worked with modeling within both credit risk and interest rate risk, throughout different roles with model development, model validation and model usage, both in smaller unsecured lenders and larger OSI institutions, currently in Nordea's model risk function.
Sessions
-
Get to know your credit losses – Get to know your business01-Dec-2026
-
Get to know your credit losses – Get to know your business01-Dec-2026Business Banking Innovation